The Primary-Source Principle: Why We Refuse to Summarize Someone Else's Summary

Think about how a piece of company news usually reaches you.
A company files a document, and its press team turns that into a release.
A wire service condenses the release, a website rewrites the wire story, and a blog post comments on the website.
By the time you read it, you are several people removed from what the company actually said.
Why every layer of retelling costs you precision
Each hop in that chain does two things at once.
It loses detail, because the writer has to cut something to fit the format.
And it adds a point of view, because deciding what to cut is a judgment call.
Neither step has to be careless or biased on purpose.
A writer simply cannot restate a 10-K without choosing which parts matter.
Do that three or four times in a row and the original wording, the specific line in a risk factor or the exact figure in a table, is gone.
What is left reads smoothly, but it is no longer evidence.
What "one hop from the source" means in practice
Our rule at Insighthread is that we never sit more than one hop from the primary source.
The primary source is the filing itself, or the earnings call transcript itself.
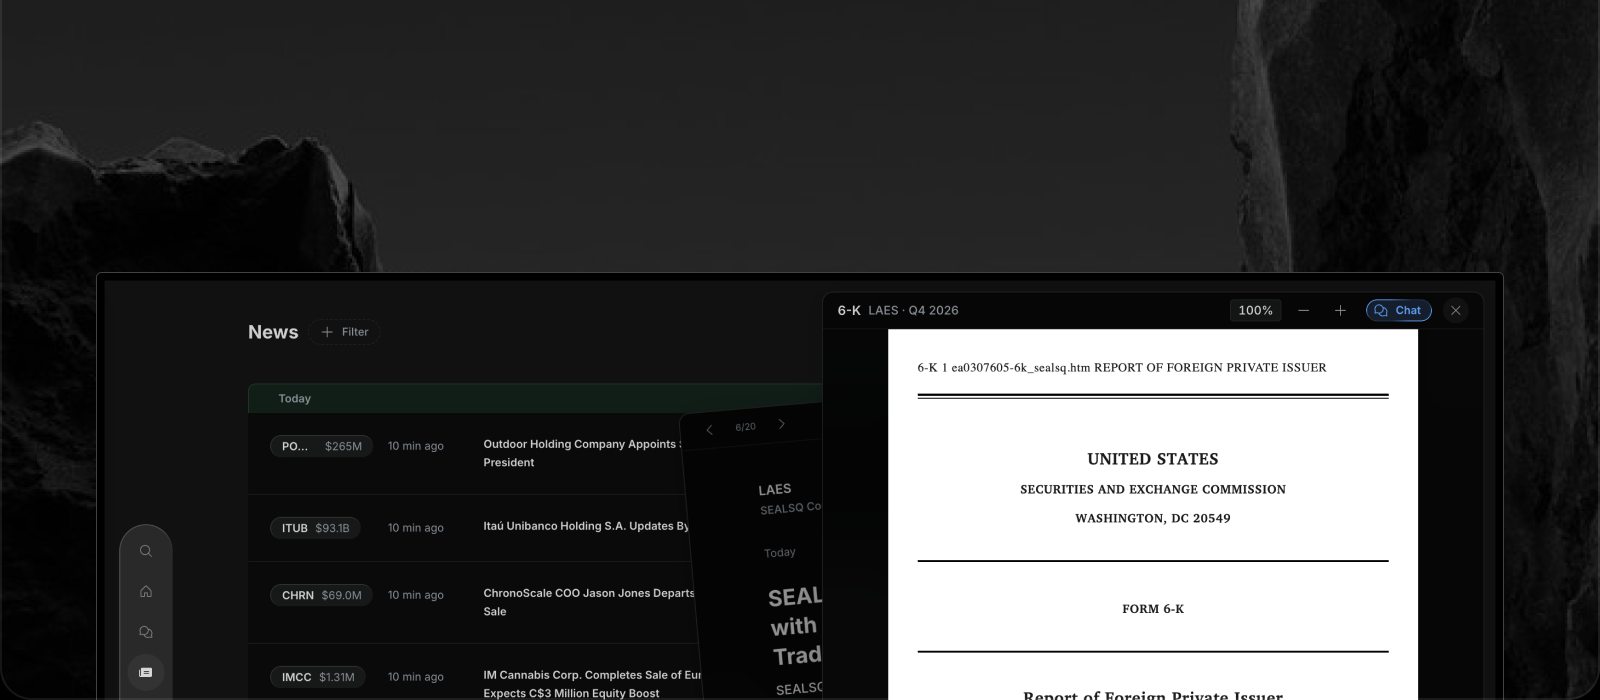
That is why every news item in the feed is generated from a filed SEC document and links to it.
It is why the business description on a company profile page comes from the company's own 10-K rather than a generic web summary.
It is also why our AI analyst works from filings and transcripts, not from commentary about them.
This is a stricter commitment than the one in Why Insighthread Only Reads SEC Filings, which describes what we use.
This post is about why we hold the line.
Why secondhand information is a design smell
In software, a "code smell" is a sign that something deeper is wrong.
We treat secondhand information the same way.
If a feature needs someone else's summary to work, the feature is built on the very layer we are trying to avoid.
That has real consequences for the product.
It is why we do not build an aggregated "market sentiment" score that boils down other people's opinions.
Such a number might sell well, and it would look impressive on a dashboard.
But it would be a summary of summaries, and we would be unable to show you what it was made of.
A rule that rules things out is only useful if it costs you something, and this one does.
A simple test for any financial claim
You can apply the principle without using our product.
When you read a claim, ask how many hops it is from the document.
If the article links to the filing, you can check the claim yourself in a minute.
If it links to another article, you are one hop further away, and the next question is what that article rests on.
The longer the chain, the more you are trusting the retellers instead of the record.
Often that trust is fine, but it should be a choice you make knowingly.
Closing the gap between the headline and the filing
The goal is that you never have to wonder whether a summary is faithful.
You see the short version, and the source behind it is one click away.
That is also why our items are short, which we cover in Why Financial News Should Be 60 Words, Not 600.
If you want to see the principle in action, open an item in the news feed and look at the Sources section at the bottom.